Foxconn-OpenAI Deal & the AI Bubble Debate (2026)
Foxconn says a new OpenAI deal is coming and AI isn't a bubble. We test the claim against record Q3 sales, Big Tech capex and the risks.
TL;DR
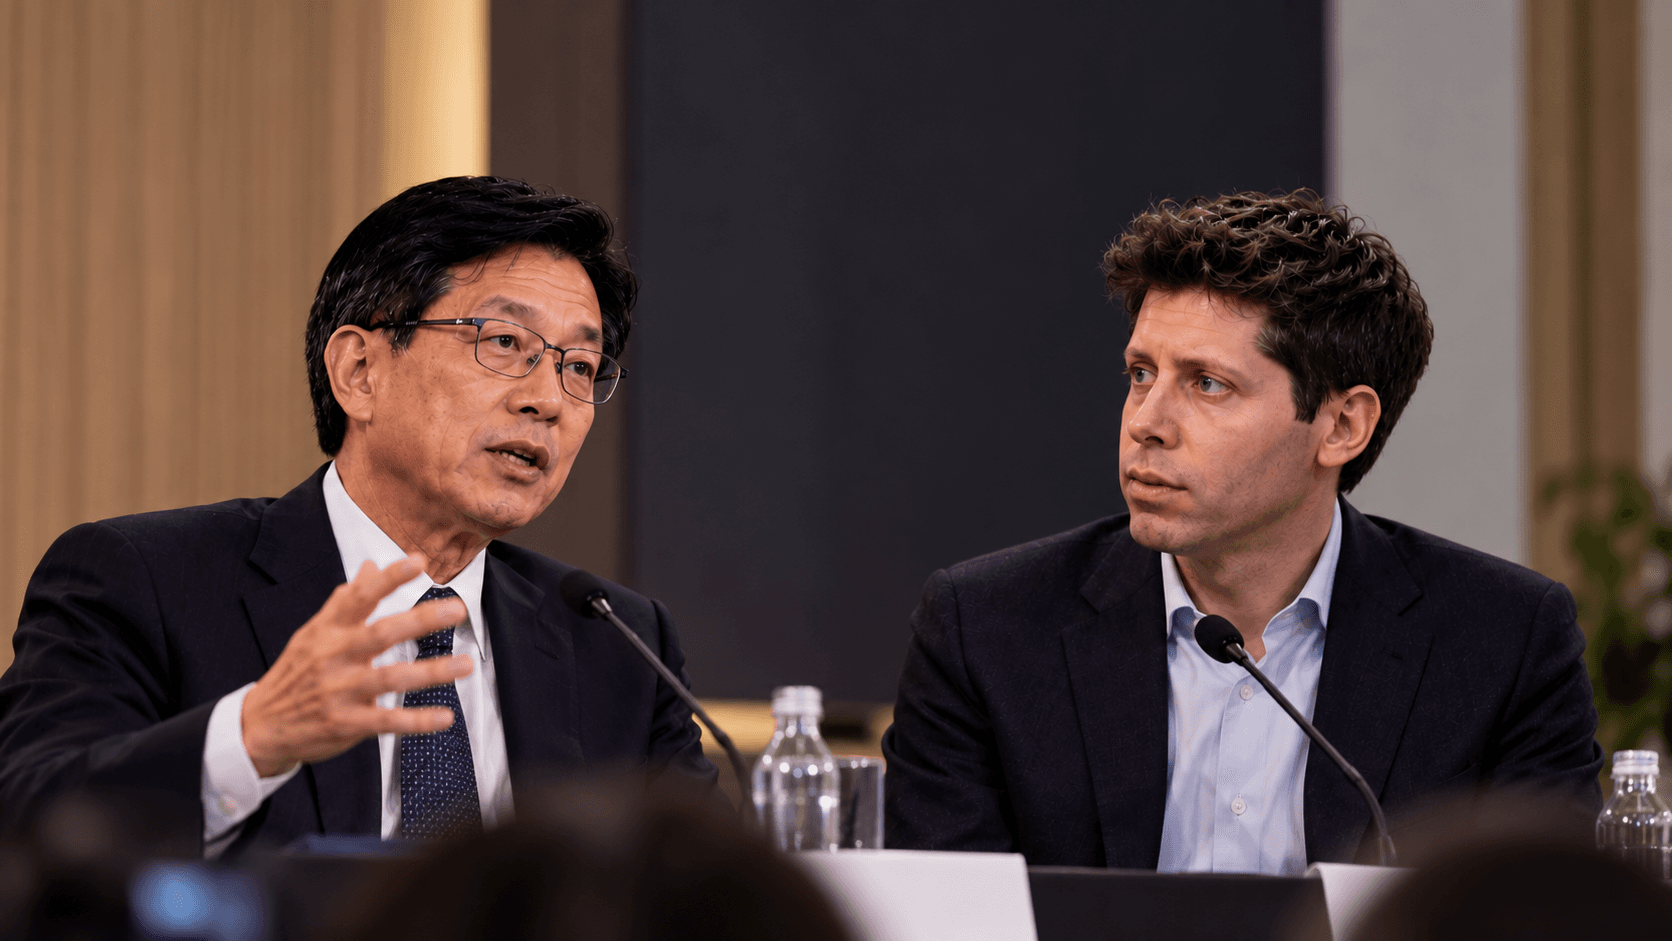
The news: On Oct 30, 2026, Foxconn chairman Young Liu met Sam Altman and said a new OpenAI collaboration is coming. No terms were shared. It builds on a Nov 2025 rack-design pact that had no purchase commitments.
The numbers behind “no bubble”: Foxconn posted record Q3 revenue of NT$3,026.9 billion (+47.12% YoY). September sales crossed NT$1 trillion for the first time. Cloud and networking, mostly AI servers, made up 51% of Q2 revenue.
The catch: Foxconn’s biggest buyers are stretching their finances. Alphabet’s free cash flow was –$9.1 billion in Q3, and Amazon spent $77.3 billion on capex in one quarter. Foxconn wins while the spending lasts, but it is not a neutral judge of whether the spending pays off.
What to watch: The formal OpenAI announcement, Foxconn’s Q3 results on Nov 12, and Nvidia’s next report
Foxconn working on a new tie-up with OpenAI, says there is no AI bubble
Foxconn says a second OpenAI deal is coming and that AI is not a bubble. Its own results back up the growth story: record revenue, with AI servers now more than half of sales. But no deal terms are public, and Foxconn earns money on every AI rack it ships. Treat its view as a demand signal, not a verdict.
What happened on October 30
At its annual Hon Hai Tech Day in Taipei, chairman Young Liu said he had met OpenAI CEO Sam Altman earlier that morning. He said an announcement would follow once details were final. He gave no scope, size or timeline.
Liu also made three other points:
The AI industry is not in a bubble, and Foxconn expects double-digit growth next year.
Foxconn has six factory buildings in Houston making AI servers for Nvidia, and it needs more space.
In a separate interview, he put Foxconn’s global AI server share at about 40%, with a goal of 45% next year and 50% within a couple of years. He said capacity is booked for at least the next 18 months, and he warned that overinvestment could hurt the company.
Investors stayed cautious. Foxconn’s shares closed down 1.01% at NT$245.50, and Taiwan’s main index fell 2.49% on worries about AI returns.
What the 2025 OpenAI deal covered
The new tie-up builds on an agreement announced on November 20–21, 2025. Under it:
The two firms would co-design several generations of AI data-center racks.
Foxconn would make cabling, networking, cooling and power systems at its US sites.
OpenAI would get early access to evaluate the systems, plus an option to buy.
Neither side took on purchase commitments or financial obligations.
Foxconn’s numbers: AI servers now run the company
Foxconn’s cloud and networking segment has grown from a third of sales to a majority in two years:
FY2024: 30% of revenue
FY2025: 40%
Q1 2026: 48% (revenue NT$2.13 trillion)
Q2 2026: 51%, the first time above half (revenue NT$2.53 trillion, +41% YoY)
The Q2 2026 results set a second-quarter profit record. Net profit was NT$59.97 billion (+35% YoY), with earnings of NT$4.27 per share. Margins were thin: 6.12% gross, 3.75% operating and 2.37% net.
Q3 was bigger. The company’s September revenue report shows:
Q3 revenue: NT$3,026.9 billion, up 47.12% YoY.
September alone: NT$1,158.6 billion, the first month above NT$1 trillion.
First nine months: NT$7.67 trillion, up 39.53%.
Foxconn expects AI growth to continue in Q4 and said AI rack shipments would more than double in 2026. Rotating CEO Michael Chiang has set a target of 50% of the AI server market built on Nvidia’s Vera Rubin platform next year.
The AI bubble debate in numbers
Liu spoke during a sharp selloff. Alphabet’s shares fell 12.6% in one session this week, their worst day since the company began trading in 2004. The trigger was its Q3 report, which showed free cash flow of –$9.1 billion and capex of $51.4 billion for the quarter. Its 2026 capex outlook is $195–205 billion, with a “significant” rise expected in 2027.
Other big AI buyers show the same pattern:
Amazon: Q3 capex of $77.3 billion, a 2026 outlook near $220 billion, and trailing free cash flow of –$42.4 billion.
Meta: Q3 capex of $34.91 billion and a 2026 outlook of $135–145 billion.
Microsoft: Azure grew 48%, beating its own guidance.
Bond markets reacted too. The 10-year US Treasury yield slipped to about 4.92% after touching 5.36% earlier in October, its highest since 2002. Higher borrowing costs make debt-funded data centers harder to justify.
Demand itself still looks strong. Nvidia’s latest quarterly results showed data-center revenue of $89.0 billion (+117% YoY) and guidance of $108 billion ± 2% in total revenue for the next quarter.
The risk sits with the buyers. Reported investor materials show OpenAI expects about $856 billion in compute spending and $278 billion of cumulative negative free cash flow from 2026 to 2030.
Houston, tariffs and the US build-out
Foxconn’s Houston campus is central to Nvidia’s US server plans. Nvidia’s October 2025 announcement described a 242,287-square-foot Foxconn AI hardware factory there. A Texas filing lists a further $71.91 million fit-out of 74,312 sq ft, scheduled from September 2026 to January 2027. Foxconn also has US sites in Wisconsin, Ohio and California.
Trade policy explains much of the rush. A 25% Section 232 tariff on certain advanced chips took effect on January 15, 2026. Mexico supplied 43.7% of US computer imports in May–July 2026, so building in the US helps hedge tariff and border risk.
Humanoid robots: more than 10 at work in Texas
The chairman of Foxconn Industrial Internet (FII), Brand Cheng, says more than 10 humanoid robots now work in Foxconn’s Texas facilities for internal use, with more sites planned. FII showed two wheeled models in October. One lifts items vertically, and the other bends at the waist for assembly and loading. The robot AI is built on Nvidia’s GR00T foundation model.
For scale, a major investment bank raised its forecast to 6.48 million humanoid units by 2035, a $138 billion market, up from 1.38 million. Ten robots is a pilot, not a business line yet.
What this means for Foxconn and OpenAI
The deal’s value depends on firm orders. A second design pact adds prestige but little revenue. A deal with volume commitments, or US-built racks for OpenAI’s data-center projects, would be material. Until terms appear, its financial impact is unknown.
“No bubble” comes from an interested party. Foxconn earns on every rack it ships, whether or not the buyer ever earns a return. Its record sales show that customers are spending. They don’t show that the spending is profitable.
Concentration is rising. More than half of revenue now comes from one segment tied to one chip platform and a few large buyers. One major bank estimates Foxconn’s share of high-end AI racks could fall to 39% in 2026 from 51% in 2025 as buyers add suppliers. That sits awkwardly with Liu’s 40%→50% target. The two figures likely measure different markets.
Margins leave little room. A 6.12% gross margin means Foxconn needs huge volumes. If volumes stall, profits shrink fast.
The bull case:
Capacity is booked about 18 months ahead, with the Vera Rubin ramp still to come.
Foxconn expects hyperscaler capex to pass $1 trillion in 2027.
Partnerships with OpenAI, Nvidia and Schneider Electric widen its customer base.
US factories hedge tariff risk.
The bear case:
Big buyers are running negative free cash flow and funding spending with debt.
Higher rates raise the cost of AI build-outs.
Rivals may take rack share.
Single-digit gross margins leave little buffer.